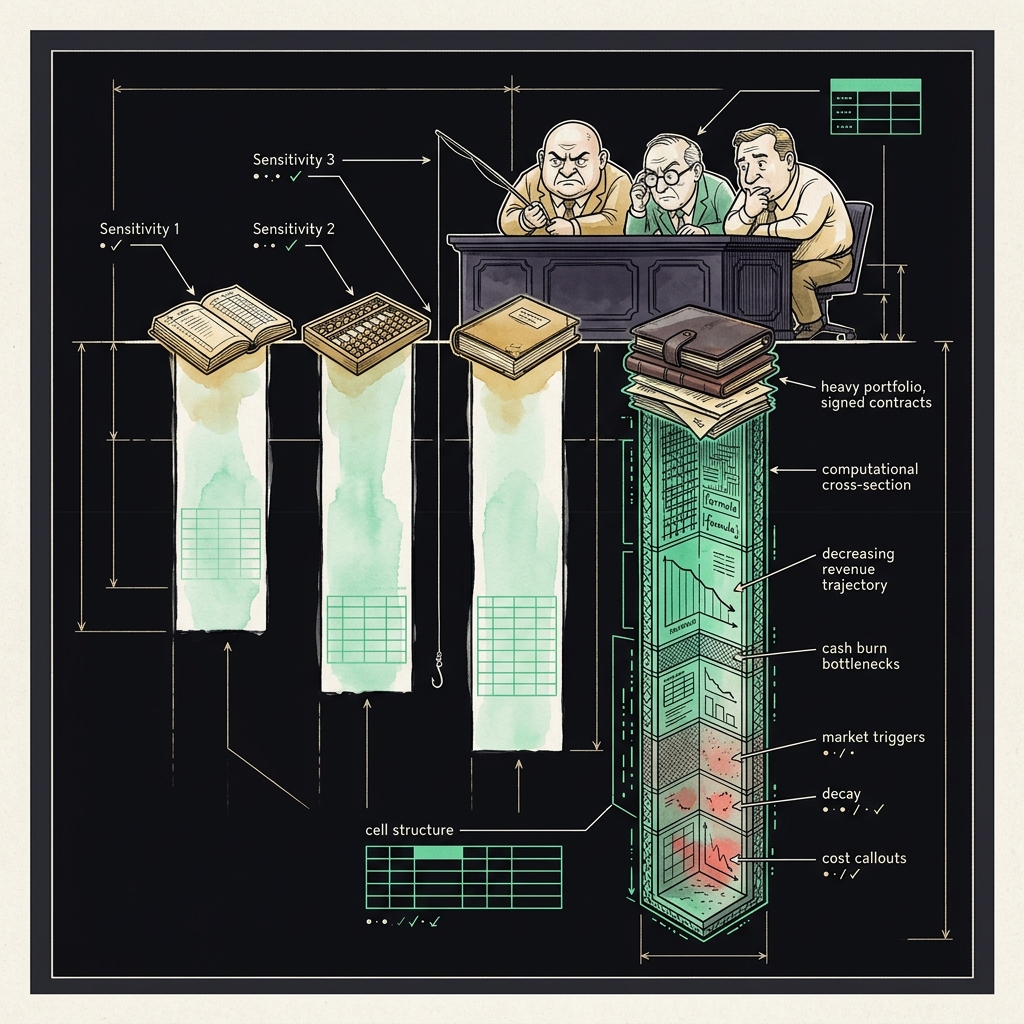
An IC memo downside scenario is a single, fully-modeled loss case that walks the investment committee through the specific mechanism by which the deal loses money, including revenue trajectory, cash burn, covenant breaches, and equity impairment. Unlike a three-variable sensitivity table that varies inputs in isolation, one loss case forces the sponsor to defend a coherent story about how the company breaks. This is what committees actually debate.
Sensitivity tables have their place, but they lose the room. A tornado chart showing revenue growth at 5%, 10%, and 15% tells the IC nothing about what happens when the CFO quits, the top customer churns, and refinancing markets close in the same quarter. The IC memo downside scenario depth question is the difference between a memo that gets approved conditionally and one that gets approved with conviction, or killed cleanly. This guide walks through how to build the one loss case that beats three sensitivities, with an Excel template structure senior deal partners actually use.
Why Sensitivities Alone Fail in IC Discussion
KKR co-founder Henry Kravis has repeated a version of the same line in interviews and letters since the 1980s: "Any jerk can buy a company. It's what you do with it that counts." The corollary at the IC level is that any associate can run a sensitivity. It's whether you can defend a specific loss path that counts.
Sensitivities have three structural weaknesses that show up under committee pressure:
- They vary one input at a time. A -20% revenue case with the rest of the model held constant is a fiction. In real distress, revenue contraction, margin compression, working capital drag, and covenant breach arrive together.
- They obscure the mechanism. A cell that reads "MOIC: 0.6x" at 5% growth does not tell the IC why growth fell to 5% or what management would be doing about it.
- They invite anchoring on the base case. When the downside is a column adjacent to the base, the committee reads it as a 15% haircut on a plan they already believe. It stops being a real risk.
The Bank of England's 2024 Financial Stability Report noted that in the leveraged loan market, "amend-and-extend" activity hit record levels in 2023-2024, with sponsors deferring maturities rather than confronting impaired capital structures. Deals that priced with three-column sensitivity tables ended up in workout with covenant packages nobody had modeled coherently.
Practical takeaway: Before the memo goes into the pre-read pack, ask: does the downside describe a world, or does it just describe a column? If it's a column, rewrite it.
The Anatomy of a Loss Case That Holds Up in Committee
A loss case is a narrative wrapped around a fully-linked three-statement model. The narrative names the trigger, the transmission, and the terminal state. The model shows the cash flow path, the covenant path, and the equity path over the hold period.
The structure that partners at firms like Apollo, Ares, and Blackstone use in credit committee memos, based on the disclosure patterns visible in their BDC 10-Q filings, follows a five-block format:
- Trigger event. A specific, dated, plausible catalyst. Not "market downturn." Something like: "Anchor customer (28% of revenue) does not renew the 2027 master services agreement, citing consolidation onto a competing platform."
- Transmission mechanism. How the trigger propagates through the P&L, balance sheet, and cash flow. Revenue drops in Q1 2027, gross margin compresses 400 bps as fixed costs stay flat, working capital swings unfavorable as receivables age.
- Covenant path. Where and when the credit agreement breaks. Fixed charge coverage below 1.10x by Q3 2027, total leverage above 6.5x by year-end.
- Management response. The realistic set of levers management would pull, priced with an assumed success rate. Cost takeout of $8M annualized (assume 60% realization), sale-leaseback of the Austin facility for $22M net proceeds, hiring freeze.
- Terminal state. Where the equity lands. MOIC, IRR, capital-at-risk-realized, and whether the credit facility recovers par.
The five blocks belong on one page in the memo body. The supporting Excel model sits in the appendix. The IC reads the page; the associate defends the appendix.
Practical takeaway: Draft the trigger sentence first. If you cannot write a specific, dated, plausible catalyst in one sentence, you do not yet have a downside case. You have a spreadsheet.
How to Build the Loss Case in Excel: A Step by Step Model Structure
The spreadsheet model behind the loss case is a variant of the base three-statement operating model, not a separate file. Building it as a switchable scenario keeps the linkage tight and the audit trail clean. Wall Street Prep and Breaking Into Wall Street both teach this structure in their financial modeling courses, and it maps to what senior associates at Goldman Sachs and Morgan Stanley are expected to produce for pitch committees.
The build sequence for the loss case scenario in a leveraged buyout or growth equity model:
- Scenario toggle. Add a driver cell (usually B3 or B4 on the assumptions tab) with values 1 = Base, 2 = Upside, 3 = Downside. Every driver line uses
CHOOSE()orINDEX()to pull the right row. - Revenue architecture. Break revenue into volume x price x mix, and hit the specific line the trigger touches. If the trigger is customer loss, that means a specific cohort of customer revenue drops to zero on the renewal date, not a blended growth haircut.
- Cost linkage. Split costs into variable, semi-variable (steps), and fixed. In distress, the fixed cost base is what kills you; make sure the model does not silently flex it down.
- Working capital drag. Extend DSO by 15-25 days in the trigger year. Slower payers hit cash before they hit the P&L; this is the single most common modeling omission in first-draft downside cases.
- Covenant calculation block. A dedicated section that computes leverage, fixed charge coverage, and interest coverage on the credit-agreement definition (not GAAP). Test each quarter against the covenant schedule.
- Cure and workout logic. If a covenant breaks, model the sponsor's actions. Equity cure (if permitted, capped in most agreements at four quarters over the deal life), waiver fee, amend-and-extend, or default. Each has different equity implications.
- Returns roll-up. A summary tab that shows MOIC and IRR by scenario, with the loss case highlighted. Include "money multiple on incremental capital" if the sponsor is likely to fund a rescue equity round.
A free download of a scenario-toggle Excel template lives in the ModelStack IB & M&A category, structured exactly this way. The point of using a ready-made spreadsheet model is that the covenant block and the cure logic are the parts junior team members always get wrong under time pressure, and getting them wrong in an IC memo is the kind of thing partners remember.
Practical takeaway: Build the covenant block before you build the returns block. If the covenant math is not right, the equity math does not matter.
How to Present One Loss Case in the IC Memo
The presentation format matters as much as the modeling. IC members read a lot of memos. They will read yours in eight minutes on a plane. The loss case has to survive that reading and then reward a second read on the ground.
The Blackstone 2024 annual letter to shareholders, published by CEO Steve Schwarzman in February 2025, emphasized that Blackstone's underwriting discipline centers on "what could go wrong" being modeled with the same rigor as the base case. That discipline shows up in the memo format:
- One page, five blocks. Trigger, transmission, covenant path, management response, terminal state. Not five pages. One.
- A single chart. Free cash flow through the hold period, base case and loss case, with covenant breach dates marked. No stacked bars, no waterfall gymnastics.
- A capital-at-risk number. The dollar amount the fund could lose, gross of any recovery. This is the number the IC chair will circle. Make sure it is defensible in isolation.
- An "if this happens, we do what" sentence. The sponsor's response plan, in one sentence. "If revenue drops below $180M in 2027, we replace the CEO within 90 days and pivot the go-to-market to a channel model."
- The exit assumption in the loss case. This is where associates hide optimism. If the base case exits at 12x EBITDA and the loss case exits at 11x, the loss case is not a loss case. Distressed exits price at 6-8x for quality businesses and lower for anything else. Look at the S&P LCD data on distressed exit multiples if you need a source.
The three-sensitivity table can still appear in the appendix. It just cannot be the answer to "what happens if this goes wrong." That answer belongs on one page, with a name, a date, and a mechanism.
Practical takeaway: Write the capital-at-risk number in the memo header. If you are afraid to put it there, the loss case is not conservative enough.
Common Failure Modes and How Senior Partners Catch Them
Watching IC discussions across mid-market and upper-middle-market funds, the same critiques recur. Partners with fifteen or twenty years of committee time develop pattern recognition for weak downside cases. The critiques below track what shows up in memos that get sent back for rework:
- The 20% haircut trap. Revenue down 20%, everything else the same. This is the modeling equivalent of "assume a can opener." Real revenue contractions come with margin compression, working capital drag, and management turnover.
- The perpetual growth error in distress. A model that shows revenue troughing in year 2 and then growing 15% annually to a full exit multiple in year 5 is not a loss case. Distressed businesses do not compound out of trouble on a smooth curve.
- Ignoring the credit agreement. If the covenant package is not modeled on its actual definitions (EBITDA add-backs, cure rights, baskets), the leverage number is fiction. This is the single most frequent partner-level rewrite request.
- Recovery assumed at par. The credit facility does not get repaid at par in a workout. Historical recovery data from Moody's on first-lien loans in the 2020-2023 vintage shows recoveries in the 65-75% range for defaulted deals, not 100%.
- No management action. Real management teams do things when the company breaks. Modeling zero response is unrealistic. Modeling perfect execution of the response is also unrealistic. Assume partial success with a stated haircut.
Bain & Company's Global Private Equity Report 2024 highlighted that fund-level returns in the 2018-2020 vintage are being drawn down by a small number of impaired deals where downside cases were not modeled with sufficient depth. The report noted that deals that later required rescue capital were disproportionately those where the original IC memo carried a sensitivity table in place of a scenario.
Practical takeaway: When you finish the loss case, hand it to a partner who was not on the deal and ask them to red-team the trigger. If they can name a more plausible failure mode in under a minute, use theirs instead.
Building the Muscle: Making Loss-Case Discipline Repeatable
Loss-case discipline is a firm-wide habit, not a memo-by-memo effort. The funds that carry it consistently, based on the disclosure patterns of firms like Ares Management and Blue Owl in their public credit BDCs, build three practices into their process:
- A standing loss-case library. Every deal, closed or passed, gets its downside scenario archived. Two years in, the associate pool has fifty precedents to draw on and can move faster.
- A post-mortem cadence. Deals that underperform get compared back to the IC memo's downside case. If the actual outcome was worse than the modeled loss case, the memo template gets updated.
- A pre-mortem on new commits. Before final IC, the deal team runs a session where each member writes down, independently, the most likely reason the deal will lose money. The scenarios that show up on multiple lists get modeled.
The ModelStack IB & M&A template kit includes an IC memo skeleton with the five-block downside structure, a scenario-toggle three-statement model with the covenant block wired in, and a loss-case archive worksheet. Using a pre-built spreadsheet model spares the deal team from rebuilding the covenant math on every new opportunity, and it standardizes what the IC sees across deals. The free download version of the base scenario template covers the toggle mechanics; the full IB & M&A kit adds the covenant calculation block, cure logic, and workout mechanics.
A committee that sees the same five-block downside on every memo starts asking harder questions faster. That is the compounding value: not the individual memo, but the collective calibration of the group.
The three-sensitivity table is not wrong, it is just not enough. One coherent loss case, with a trigger, a mechanism, a covenant path, a management response, and a terminal state, gives the investment committee something to argue with. That argument is where the actual risk work happens. Everything else is decoration.
Sources
- Bank of England Financial Stability Report, June 2024
- Bain & Company Global Private Equity Report 2024
- Blackstone Shareholder Letter, February 2025
- Moody's Investors Service, Annual Default Study, 2024
- S&P Global Market Intelligence, LCD Leveraged Loan Data
- Wall Street Prep, LBO Modeling Guide
- KKR Insights, Henry Kravis interviews and commentary
Related: Browse all Investment Banking & M&A Templates on ModelStack.
Get started with a free template
Download our free Unit Economics Calculator — no signup required.